Can I get a mortgage in Spain as a non-resident? Documents, income and equity
Planning a Spanish loan for overseas property? This checklist explains the documents, income evidence and creditworthiness lenders require for a non-resident mortgage in Spain, followed by the process from first enquiry to the notary appointment.
Which three things do you need to get a Spanish mortgage as a non-resident?
To get a Spanish mortgage as a non-resident, you need an NIE, complete proof of income and enough equity. Spanish banks typically lend up to 70 % of the lower of purchase price and tasación, so you need roughly 40 to 43 % of the price from your own funds including purchase costs. For a small financing, employees need at least €3,500 net per month and self-employed applicants at least €80,000 profit per year.
Non-resident mortgage in Spain: the employee checklist
Employees need the NIE number, the last 2–3 payslips, the income tax assessment, 3–6 months of bank statements, the employment contract and proof of equity.
- NIE, payslips, tax assessment, bank statements: NIE number, last 2–3 payslips, income tax assessment, 3–6 months of bank statements, employment contract and proof of equity. The self-employed add financial statements and business analyses. Getting your NIE.
- Around 40–43% of the price from own funds: At 70% LTV roughly 30% plus 10–13% purchase costs, about 40–43% of the price. A German property can serve as equity via a second-charge mortgage. Costs of buying in Spain.
- All monthly obligations capped at 35% of net income: The mortgage payment plus all other monthly obligations may not exceed 35% of net income — the yardstick Spanish banks apply to non-residents. The Spanish banks.
- What decides whether a Spanish bank approves a non-resident mortgage? You need three things: the Spanish foreigner’s tax number (NIE), complete income evidence for the last two to three months plus tax assessments, and enough equity.
Spanish banks typically lend non-residents up to 70 % of the lower of purchase price and tasación (the bank's own valuation); you cover the rest and all purchase costs yourself.
The decisive figure is the debt ratio: your total monthly commitment — the Spanish instalment plus any existing German obligations — should not exceed roughly 30 to 35 % of your net income.
Employees provide payslips and their employment contract; self-employed applicants provide three annual accounts. If a document is missing, an application may fail at a lender whose requirements do not fit the case. Choosing the right bank matters.
A comparison of several lenders helps identify the bank that can assess your circumstances.
Document checklist for employees
Spanish banks apply stricter mortgage requirements to non-residents than to local borrowers. They generally require the following documents, and most now require a certified translation:
- Passport or ID card (valid, copied on both sides)
- NIE number — mandatory before the mortgage application
- The last 2–3 payslips
- Latest income tax assessment
- Bank statements for the last 3–6 months
- Permanent employment contract or confirmation of employment
- Proof of equity (bank statement, securities account overview, sale proceeds if applicable)
- Purchase contract or preliminary contract (Arras)
- Tasación (bank valuation) — usually arranged by the bank
In the further process you will encounter two documents of key importance: the FIPRE (Ficha de Información PREcontractual), a non-binding comparison sheet that every bank issues in advance, and the FEIN (Ficha Europea de Información Normalizada), the binding offer once the bank has given its commitment. Only once you have the FEIN in hand should you sign a purchase option — in Spain, a financing condition clause in the purchase contract is usually not accepted, and a deposit paid too early is usually lost if the financing falls through.
Additional documents for self-employed applicants
The self-employed face higher hurdles in the credit assessment. Banks require the following: At least three annual financial statements or business analyses; the matching income tax assessments; a current business analysis (no older than 3 months); proof of business registration / professional licence; a credit report.
- At least three annual financial statements or business analyses
- The matching income tax assessments
- Current business analysis (no older than 3 months)
- Proof of business registration / professional licence
- Credit report
Rule of thumb: otherwise the same rules apply as for employees — up to 70 % of the lower of purchase price and tasación, roughly 30 % equity. The calculation uses the actual net figure (taxable profit less tax and social security); the instalment may take 30 to 35 % of it. There is no blanket surcharge or discount for the self-employed — it is no different in Germany.
Self-disclosure form: the starting point for your bank enquiry
So that we can quickly compare your situation with the banks, please fill in our bilingual self-disclosure form (DE/EN, printable). It summarises personal data, tax status (incl. NIE), income, expenses and available equity — the basis of every bank enquiry.
Free and without obligation · no tax or legal advice · data processed only to prepare your enquiry (see privacy).
Can you get a mortgage in Spain without equity?
The question about a mortgage without equity comes up in almost every initial consultation. The answer for non-residents is clear: it does not exist. Spanish banks lend up to 70 % of the lower of the purchase price and the Tasación; the difference to the purchase price and the purchase costs of 10 to 13 % are borne by the buyer in every case.
If you have no equity in your account, financing may still be possible with a second source of funds. For example, you can borrow against an unencumbered property in Germany. This supplies the missing funds; the Spanish bank itself does not offer 100 % financing.
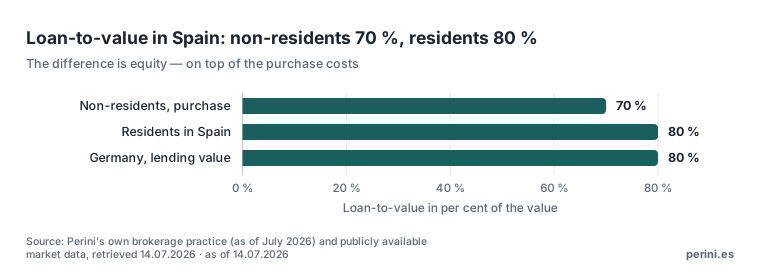
Anyone who is not tax-resident in Spain regularly gets 10 percentage points less loan-to-value than a resident. The usual ceiling is 70 % for non-residents and 80 % for residents. The difference is equity: on a purchase price of €400,000 that is €40,000, in addition to the purchase costs. 70 % is the market-standard cap, not a quirk of one individual bank.
Source: Perini's own brokerage practice (as of July 2026) and publicly available market data, retrieved 14.07.2026
If you earn outside the eurozone (CHF, USD, GBP and others), the EU-wide Mortgage Credit Directive (2014/17/EU, Art. 23) applies: if your payment burden deviates by more than 20 % from the initial value due to exchange rate fluctuations, the bank must warn you actively and point out a possible right to convert into your home currency. The exact conditions of this right are set out in the respective loan agreement — we check this for you before you sign the contract.
How much can you afford in monthly mortgage payments?
For non-residents, Spanish banks usually apply the 35 % rule: together with other obligations (consumer loans, rent commitments in your home country), the monthly mortgage payment may not exceed 35 % of available net income.
See how the factors combine in your case in the mortgage readiness check — about a minute, including the lever that helps most.
Further reading: Spanish vs. German bank — which is better for your Spanish mortgage?
Insurance and other products linked to the mortgage
Spanish banks routinely make buildings insurance a condition of the mortgage — the property is their security, and it has to be insured before completion. Life insurance tied to the loan amount is common as well, though less universally required than buildings cover. Both are typically among the bundled products that unlock the discounted (bonificado) interest rate — see our current mortgage interest rates page for what that discount is worth and what the bundled products cost in practice.
Purchase costs: What does the purchase really cost?
Why a mortgage?: 5 arguments even with capital available.
Download the self-disclosure form (PDF)
Buildings insurance: what can the bank require?
Buildings insurance is not a legal obligation of the buyer in Spain — Article 17.3 of Ley 5/2019 allows the bank to require it. The obligation arises from the contract.
The second part of the same provision is important: the bank must accept an equivalent policy from another provider — at conclusion and at every renewal —, may not charge anything for checking it and may not worsen the terms of the loan because of it. Term life insurance is likewise not required by law.
What value the policy must cover and what is not mandatory — contents, theft, life — is explained in the wiki under Seguro de hogar.
ExampleWorked example of the 35 % rule
| Item | Amount |
|---|---|
| Monthly net income | €5,000 |
| Other monthly obligations | €500 (consumer loan) |
| 35 % limit | €1,750 |
| Maximum new mortgage payment | €1,250 |
| At 2.95 %, 20 yrs → financeable amount | ~€225,000 |
Simplified calculation. Actual assessment is made individually by the bank.
Run this calculation with your own figures →
Model calculations without guarantee. Not binding offers. Terms vary depending on credit profile, property and bank. No tax or legal advice.
Frequently asked questions
Which documents do I need for a mortgage in Spain as a non-resident?
ID card or passport, NIE number, last 2–3 payslips, income tax assessment, 3–6 months of bank statements, employment contract, proof of equity and purchase contract. The self-employed additionally need financial statements and business analyses.
What is the 35 % rule?
For non-residents, Spanish banks usually apply the 35 % rule: the monthly mortgage payment plus all other monthly obligations (consumer loans, rent) may not exceed 35 % of net income.
As a non-resident, how do I actually go about getting a mortgage approved in Spain?
Through banks with their own non-resident department, with sufficiently documented income and a loan-to-value ratio of up to 70 % of the lower of the purchase price and the tasación.
How much equity do I need at minimum?
In Spain, equity is always required. Spanish banks generally lend to non-residents up to 70 % of the lower of the purchase price and the Tasación; you are responsible for the purchase costs of 10 to 13 % yourself. This amounts to around 40 to 43 % of the purchase price from your own funds. A German property can be mortgaged on a subordinate basis to provide equity.
Can I use my German property as equity?
Yes, through a second-charge loan in Germany. If you own a property in Germany (even with an existing first loan), it can be mortgaged up to 80 %. The capital raised serves as equity for the purchase in Spain.
How long does a mortgage approval take?
3 days to 4 weeks once your documents are complete. That's a full bank approval, not just an approval in principle: a genuine, document-backed decision you can act on, not a soft indicative estimate. Self-employment, multiple income sources or premium properties call for more paperwork and can take longer.
How does a loan for overseas property actually work when the property is in Spain?
A loan for overseas property in Spain is arranged directly with a Spanish bank that has its own non-resident department — there is no separate "overseas loan" product. The bank values the property itself, lends up to 70 % of the lower of that valuation and the purchase price, and documented foreign income counts the same as domestic income as long as it is fully traceable.
Free mortgage advice, without obligation
We compare banks in Spain and Germany for your specific situation and find the right solution — without upfront costs.
For a property loan, most banks only arrive at a workable calculation from a household net income of around €3,500 a month — for couples, the joint income counts.
Tell us where you live, how you earn and in which currency, as well as the proposed purchase price and deposit. We can identify which evidence a Spanish lender is likely to need.
Related pages
Equity release in Spain: how much paid-off property does your next purchase need?
Equity release in Spain and Portugal: ten model calculations — full purchase price financed, own funds needed only for the costs.
Private mortgage lender in Spain: when is it the right route?
Private mortgage lender in Spain: capital privado when no bank will write the case. Arranged from €500,000 — after testing the bank route, not instead of it.
Financing a house in Spain: How much can I afford based on my net income? (in German)
Financing a house in Spain: With a debt service ratio of 33 % and a loan-to-value ratio of 70 %, a net monthly income of €10,000 will cover a purchase price of up to around €827,500.
Buying property in Spain: in what order, and with which lead times?
Buying property in Spain step by step: the right order for financing, arras and the escritura — and why the condición suspensiva is the lever.
Inheritance tax Spain: what do parents and children actually pay?
Inheritance tax Spain: which region decides, what it takes from parents and children, and why the real limit sits in Germany.
NIE application for Spain: which of the three routes suits you best?
NIE application for Spain: three routes (consulate, in Spain, power of attorney). State fee around €9.84. Mandatory for property purchase and mortgage.
Residence permit (Aufenthaltserlaubnis) and mortgage (in German)
It is your tax residence, rather than your residence permit, that determines your mortgage terms under the 183-day rule; your residence permit does not affect them.
Mortgage requirements Portugal
NIF, income proof, up to 80% LTV — what non-residents actually need.
Finca on rural land
Banks value ‘suelo rústico’ more cautiously — see the dedicated page for details.
Property financing for the self-employed
Property financing for the self-employed in Spain and Portugal: Banks base their calculations on taxable profit, not turnover. What you need to provide.
Refinancing a Spanish mortgage: When is it worth switching — and when isn’t it? (in German)
The savings over the remaining term are weighed against the costs of switching: a new tasación, notary fees, land registry charges and, where applicable, early repayment charges.

Content by Siegfried Perini — local brand representative since 2019, active in real estate since 1992, entered in the German intermediary register (§ 11a GewO) as a person directly involved in brokerage and advice. Point of contact for German-speaking buyers in Spain and Portugal. Brokerage by Olga Nikushkina, mortgage credit intermediary under § 34i German Trade Regulation (GewO); in Portugal through a locally licensed intermediary.